
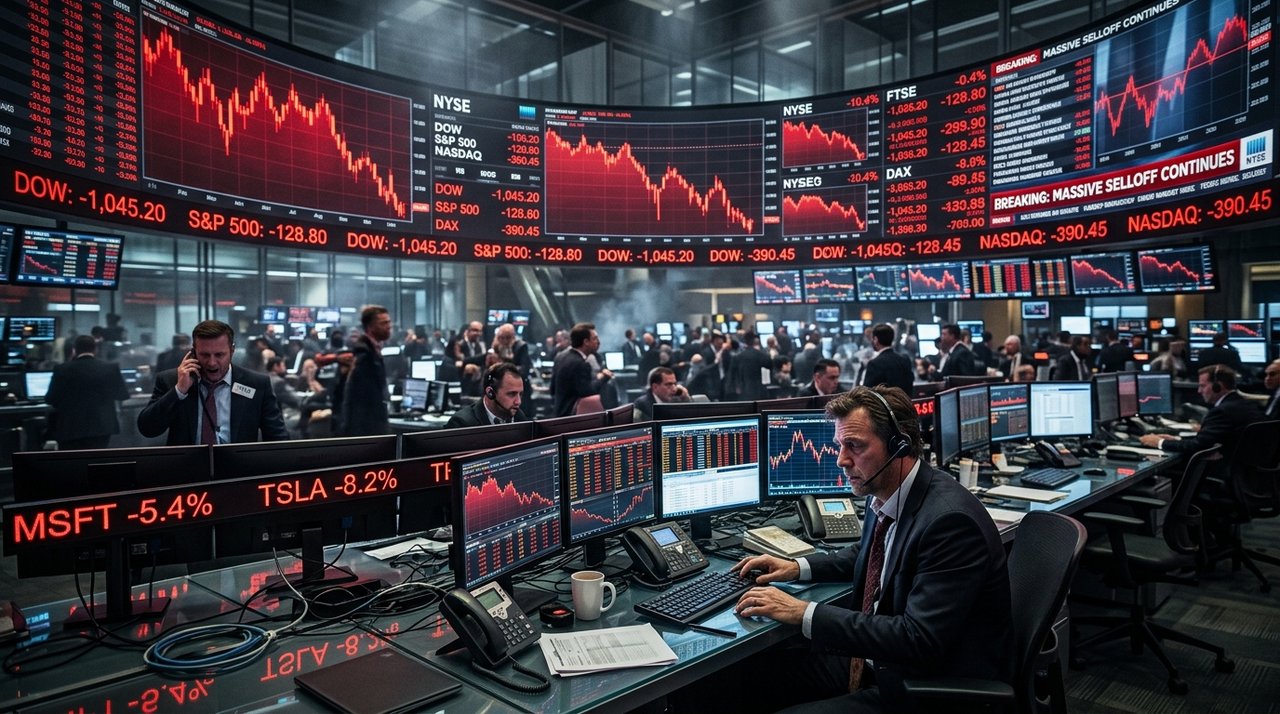
Global equity markets have encountered intense selling pressure following a stark macro note from Goldman Sachs strategists, warning that the current equity rout has substantial downside momentum remaining. As benchmark volatility gauges surge toward cyclical extremes, institutional investment desks are aggressively rotating toward defensive positioning and liquid cash reserves.
📉 Wall Street Risk Alert: Essential Takeaways
- Goldman Sachs Warning: Equity strategists indicate market drawdown conditions remain incomplete as systemic liquidity contracting persists.
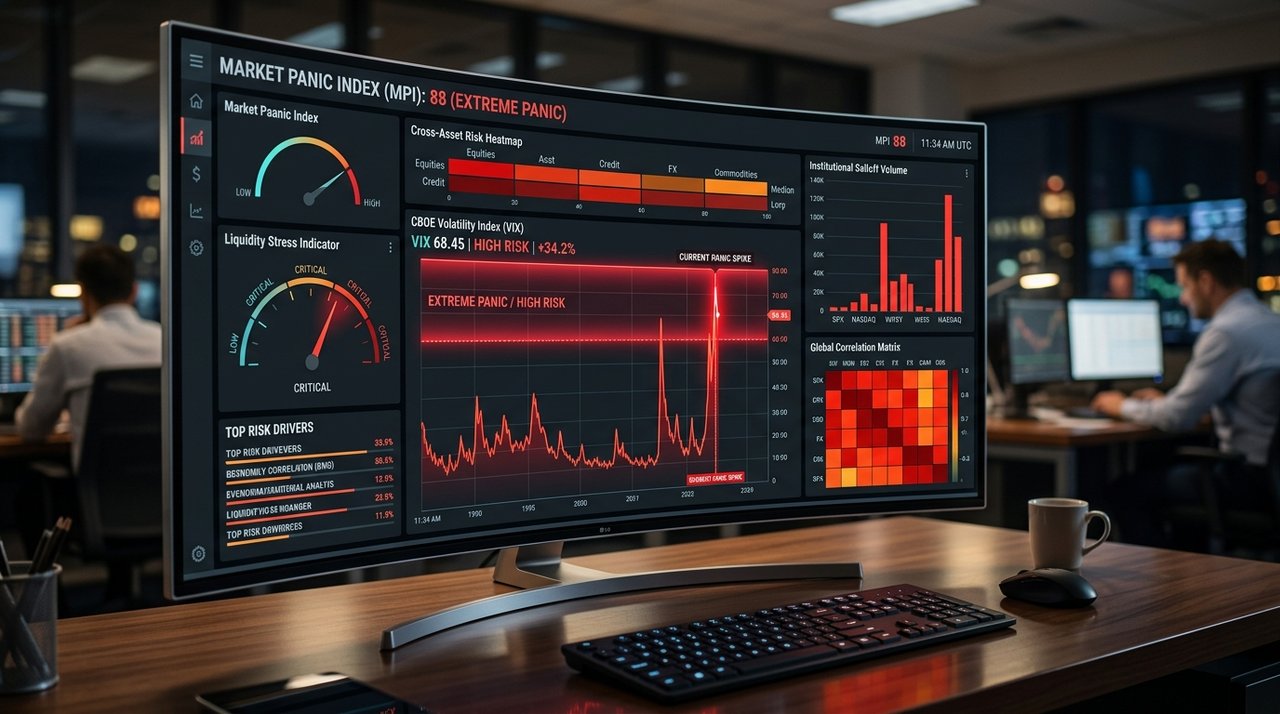
- Panic Index Spike: The CBOE Volatility Index (VIX) and cross-asset risk indicators have pierced multi-month highs, signaling widespread institutional hedging.
- Valuation Compression: Megacap technology and speculative growth sectors face severe multiple compression amidst resilient long-term Treasury yields.
- Defensive Playbook: Capital flows highlight aggressive reallocation into short-duration cash equivalents, defensive utilities, and dividend aristocrats.
1. Anatomy of the Market Selloff: Why Goldman Believes More Downside Looms
According to Goldman Sachs Chief Equity Strategists, the present selloff is not a transient technical pullback, but an orderly repricing of macroeconomic fundamentals. With the Federal Reserve maintaining rigorous policy discipline and benchmark 10-year Treasury yields hovering at restrictive thresholds, the equity risk premium (ERP) has compressed to multi-decade lows.
Institutional desks note that systematic quantitative funds and commodity trading advisors (CTAs) have initiated forced deleveraging after volatility-control thresholds were breached. This programmatic selling creates persistent overhead supply, dampening traditional "buy-the-dip" momentum.
| Market Indicator | Current Reading | Baseline Range | Risk Implication |
|---|---|---|---|
| CBOE Volatility Index (VIX) | 28.45 (+18.2%) | 12.00 – 16.00 | Extreme institutional hedging & put option buying |
| 10-Year Treasury Yield | 4.48% (+6 bps) | 3.80% – 4.10% | Sustained pressure on growth multiple valuations |
| S&P 500 Forward P/E | 19.8x (Down from 22.4x) | 16.5x – 18.0x Historical | Valuation normalization underway across megacap tech |
| High-Yield Credit Spread | 385 bps (+42 bps) | 300 – 330 bps | Widening default insurance costs in corporate debt |
2. Sector Rotation & Capital Flight Dynamics
A granular look at market internals shows severe dispersion between capital-intensive technology bellwethers and cash-flow-rich consumer staples. Semiconductors, cloud software, and speculative EV entrants have absorbed the brunt of institutional rebalancing, while consumer non-durables, healthcare, and energy producers have exhibited relative resilience.
Furthermore, money market fund assets have ballooned to historic records exceeding \$6.3 trillion. With 5% risk-free yields available in short-term government paper, institutional capital requires significantly more attractive equity risk discounts before committing fresh buying liquidity.
3. Practical Portfolio Strategy in High-Panic Regimes
Financial advisors and institutional analysts recommend maintaining strict risk parameters during elevated VIX regimes:
- Dollar-Cost Averaging (DCA): Avoid large lump-sum entries into falling assets; stagger capital deployments over predefined calendar intervals.
- Rebalancing Weightings: Trim outsized speculative positions to ensure broad index and fixed-income diversification.
- Hedging Strategies: Utilize index put spreads or capital preservation structures to mitigate tail-risk exposure without triggering taxable capital gains.
To leave a comment, click the button below to sign in with Blogger.